Welcome! Imagine a huge, global chessboard. The pieces are moving, and the players are powerful. On one side, you have the traditional telecom operators. On another, the internet giants, known as hyperscalers, who dominate the cloud. And entering from above are ambitious new satellite constellations.
Each player wants control of the most valuable squares: the customer relationship and the underlying digital platform. To see this game in action, look at regions like Africa. Insights from the Africa Digital Infrastructure Outlook 2026 show explosive growth in connectivity. This growth is fueling cloud and AI expansion, reshaping who holds the power.
You’ll see new hyperscaler partnerships forming as traditional players seek new strengths. You’ll also discover where agile mobile virtual network operators and enablers (MVNO/MVNE) fit into this puzzle. This shifting dynamic brings real challenges, including the trust and talent issues highlighted as leading sector risks.
By the end of this section, you’ll have a clear map of the board, the key players, and the high stakes of the game being played for our connected future. Let’s get started!
Porter/SWOT snap for each camp (telco, cable, cloud, satellite)
A Porter’s Five Forces and SWOT analysis gives us a clear view of the competitive landscape telecom. It’s like a health check for each player in the market.
We’ll examine four main groups: traditional telecom companies, cable operators moving into cable mobile, cloud giants like AWS and Azure, and satellite providers such as Starlink. We’ll look at their Strengths and Weaknesses, and the Opportunities and Threats they face.
First, we use Porter’s Five Forces to understand the industry. It looks at rivalry, new entrants, supplier and buyer power, and substitutes. Then, SWOT focuses on each player’s position in this landscape.
Our analysis is based on real data, like the EY “Top 10 Risks in Telecommunications” report. This turns guesses into solid insights. Are you ready? Let’s explore the snapshots.
| Camp | Strengths | Weaknesses | Opportunities | Threats |
|---|---|---|---|---|
| Traditional Telco | Nationwide physical networks, strong brand trust for reliability, millions of existing mobile subscribers. | Legacy IT systems are costly, talent gaps in new tech (EY Risk #2), slow innovation cycles. | Upgrading to 5G standalone, selling network APIs to developers, leveraging customer data for new services. | Hyperscalers as disruptors (EY Risk #8), security breaches damaging trust (EY Risk #1), price wars. |
| Cable Operator | Dominant in-home broadband, extensive local fiber, strong bundle offerings (video + internet). | Mobile network is often an MVNO (rented), less experience with wireless core technology. | Aggressive cable mobile bundles to steal telco customers, convergence of home and mobile services. | Over-reliance on a few content partners, fixed wireless and satellite as home internet substitutes. |
| Cloud Hyperscaler | Massive global compute scale, AI/ML expertise, agile software culture, developer ecosystems. | No owned last-mile access to consumers, limited experience with regulated telecom operations. | Supplying cloud-native network software (Core & RAN), hosting telco IT workloads, edge computing partnerships. | Regulatory pushback on market power, data sovereignty laws, possible backlash from telco partners. |
| Satellite Provider | Unique global coverage, rapid deployment for remote areas, government/enterprise contracts. | High upfront satellite costs, latency challenges for real-time apps, limited capacity in dense cities. | Filling coverage gaps for telcos (backhaul, direct-to-device), emergency and maritime services. | Rocket launch failures, space debris regulation, terrestrial 5G improvements reducing the gap. |
Let’s flesh out the details. For traditional telcos, the threat of new entrants is huge. It’s not just startups. It’s the hyperscalers and cable companies. EY’s report shows 76% of telco leaders see cloud giants as future disruptors. Their biggest weakness? Often, it’s their own culture and systems, making transformation slow.
Cable operators are interesting. Their move into cable mobile is a threat to telcos. Their strength is the bundled customer relationship. If they can package mobile seamlessly with your home internet, TV, and security, that’s a powerful offer. Their weakness is that their mobile service often runs on someone else’s network, which can limit control and margins.
Cloud hyperscalers change the game. They increase the “bargaining power of suppliers” in our Porter analysis. Telcos now depend on them for cloud infrastructure and AI tools. The hyperscalers’ opportunity is to become the brains of the network, while telcos remain the brawn. Their threat is regulatory; governments are wary of their influence over critical infrastructure.
Lastly, satellite providers are the wildcards. They mitigate the “threat of substitutes” for telcos in remote areas but also become substitutes themselves for fixed broadband. Their opportunity is partnership, not just direct competition. Think of them as a niche but essential piece of the global connectivity puzzle.
So, what’s the big picture? The competitive landscape telecom is no longer a straight fight between similar companies. It’s a multi-front war with different rules for different camps. Success in 2026 will depend on how well each player understands these fundamental pressures and doubles down on their unique advantages.
Where bundling wins: broadband + mobile + content + security
Think of your favorite subscription box. Now imagine applying that ‘all-in-one’ delight to telecommunications. This unlocks the secret to keeping customers happy. Bundling isn’t just about combining services. It’s about creating a valuable ecosystem that keeps customers coming back.
Why does bundling win? It’s all about loyalty and revenue. When you get everything from one provider, switching is hard. This makes customers stick with you. For the company, it means steady income and lower costs to get new customers.
Imagine subscribing to a streaming service and a meal kit. You pay one fee for lots of value. Telecom bundling works the same way. It aims to be your go-to for all digital needs.
Different players have their own ways of bundling. They use their strengths to meet customer needs. Here’s how the big players are building their bundles:
| Player Type | Core Bundling Strategy | Key Advantage | Potential Add-on |
|---|---|---|---|
| Traditional Telcos | Mobile + Fiber Broadband + TV | Existing customer trust & nationwide networks | AI-powered security using network data |
| Cable Providers | Broadband + Cable Mobile (MVNO) + Content | High-speed fixed network as a base | |
| Cloud Hyperscalers | Cloud Services + Security + Connectivity | Seamless integration with business apps | Unified collaboration tools |
| Satellite Players | Global Connectivity + Content Partnerships | Coverage anywhere, even rural areas | Specialized LEO satellite data plans for IoT |
Cable mobile providers are great at bundling. They use their internet customers to sell mobile services. This is cheap and very effective.
Then, there are the new space-based players. LEO satellite constellations offer internet everywhere. They bundle global connectivity with exclusive content or travel services. Imagine internet on your boat, plane, and cabin, plus your favorite shows. That’s a unique offer.
Traditional telcos have a secret advantage. Their network assets are key for AI. They can offer AI-enhanced security as part of a bundle. This turns a cost into a premium value.
This shift is about new business models based on value, not just access. Bundling broadband, mobile, content, and security meets customer needs for simplicity and protection. It turns basic access into a compelling experience.
So, who wins the bundling game? The player that combines its strengths with what customers need. The goal isn’t just to provide a connection. It’s to offer a complete digital lifestyle.
Cloud RAN and core: who supplies, who operates, margin effects
The move to Cloud RAN is like switching from a dedicated game console to a flexible gaming PC. It changes how networks are built and managed. This shift, along with core network virtualization, is at the heart of the industry’s change. Let’s look at the big questions: who makes the gear, who runs it, and what’s the impact on profits?
First, the suppliers. The market is getting crowded and competitive! Giants like Ericsson and Nokia are racing to offer cloud-native solutions. But they face tough competition from IT and cloud software specialists like VMware and Mavenir. The game is now about software platforms and tools that make a cloud RAN system work.
So, who runs this new software-defined network? This is where it gets really interesting. Telcos have a big advantage: their real estate. They have thousands of central offices and cell sites, plus miles of fiber. This is perfect for hosting the data centers needed for Cloud RAN. This physical advantage makes telcos strong contenders to operate their own cloud-native networks.
Let’s talk about margins—the ultimate business effect. Moving to a cloud-based model changes costs from big upfront expenses to ongoing ones. This can free up cash. But, the profit pool might change. If telcos buy software from hyperscalers, those cloud companies get more value. But if telcos use their assets to build and operate the cloud, they keep more margin. The goal is to make their network agile and support new services faster and cheaper.
In short, Cloud RAN is more than a tech upgrade. It’s a battle for control and profit in the new network era. Suppliers are evolving, operators have a unique advantage with their assets, and the margin story will decide the winners.
Partner plays: co‑sell, reseller, marketplace listings
In today’s world, going it alone is not enough. The game of connectivity is all about working together. Think of it like a chess game: even the strongest piece needs others to win.
Big names like EY warn about the dangers of going solo. Ineffective engagement with external ecosystems and failure to mitigate value chain disruption are major risks. Without good partnerships, you could fall behind.
This section is your guide to smart teamwork. We’ll explore the three main types of partner plays. You’ll learn how to turn rivals into allies for growth.
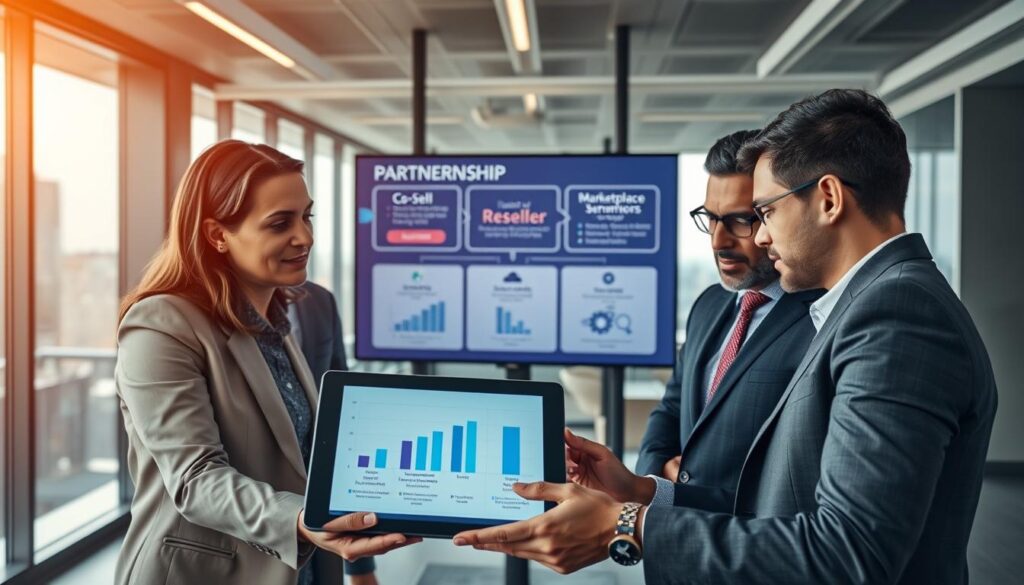
Co-selling: The Joint Venture Mindset
Co-selling is like forming a superhero team. Your company and a partner team up to win customers you couldn’t get alone. You share the customer relationship, sales effort, and rewards.
How does it work? Your sales teams work together from start to finish. This is common in hyperscaler partnerships. Think of a regional telco teaming up with Microsoft Azure or Google Cloud.
The telco brings trust and local support. The hyperscaler brings the global cloud platform. Together, they offer a complete, secure solution. This builds loyalty and opens doors to bigger deals.
Reseller Agreements: Leveraging Existing Channels
Reseller agreements are like franchises. One company lets another sell its product or service under its own brand.
This is great for quick market entry without building your own network. The MVNO/MVNE model is a classic example. An MVNO buys network access from a big carrier and sells mobile plans under its own brand.
This lets the MVNO focus on marketing and customer service. The network owner gets to use extra capacity. It’s a win-win that fuels innovation and choice for consumers.
Marketplace Listings: The Digital Storefront
Welcome to the app store for business services. A marketplace is a digital platform where vendors list their products. Customers can browse, compare, and buy easily.
For example, AWS or Azure has a huge online marketplace. Independent software vendors (ISVs) list their apps there. Telcos can also create marketplaces for smart home security or streaming content.
Listing your service on a major marketplace gives you instant visibility to a huge audience. It’s like setting up a shop in the world’s busiest mall. The platform owner handles billing and infrastructure, so you can focus on your product.
| Partner Play Model | How It Works | Best For | Real-World Example |
|---|---|---|---|
| Co-selling | Two companies jointly engage a customer, sharing resources and revenue. | Complex solutions requiring multiple expertise (e.g., cloud + connectivity). | A telco and a hyperscaler partnering to sell a unified communications package to a large business. |
| Reseller Agreement | One company sells another company’s service, often under its own brand name. | Rapidly entering new markets or customer segments without new infrastructure. | An MVNO reselling wireless service using a major carrier’s network to target a specific demographic. |
| Marketplace Listing | Your service is listed on a digital platform where many customers come to shop. | Scalable, product-led services that can be easily compared and purchased online. | A cybersecurity firm listing its firewall software on the AWS Marketplace for businesses to deploy instantly. |
So, when should you compete and when should you collaborate? The rule is simple. Compete on your core strengths—the things that make you uniquely valuable. Collaborate on everything else.
That network you spent billions building? That’s a core strength. The billing software for a niche industry? Maybe that’s a perfect marketplace listing. By mastering these partner plays, you build a more resilient business. You engage ecosystems effectively and protect your place in the value chain.
Start by asking: “Where can a partner help us grow faster?” The answer might just be your next big move.
Field notes: what to ask competitors at events (ethically)
At Mobile World Congress or Network X, the telecom world comes alive. You see telcos, hyperscalers, and satellite operators all around you!
Getting real-time insights is an art. It’s about learning through talking, not asking for secrets. It’s like improving your listening skills for strategy.
Begin with questions about partnerships. Ask, “How do you work with cloud providers to reach new markets?” This shows their plans without revealing money details.
Open up about technology adoption. Ask, “What’s surprised you most in your Cloud RAN trials?” This focuses on common challenges everyone faces.
Discuss market challenges together. Try, “Which customers like your new security bundle?” This talks about shared customer behaviors and trends.
These field notes turn simple talks into valuable insights. Asking smart questions helps you understand the telecom world better. You leave with a clearer plan for 2026, not secrets.